Research
Insulin Pumps ’26: How new tubeless pumps could shift manufacturer share
What 51 US physicians (41 endocrinologists, 10 primary care) expect for pump market penetration through 2028, manufacturer share, the tubeless launches, and GLP-1 drugs.
Overview
Rival tubeless pumps are coming to a patch pump market led by Insulet’s Omnipod, and GLP-1 drugs are changing which type 2 patients start a pump. We asked physicians how far pump use will grow through 2028, which manufacturers will gain or lose share and why, how they rank the new patch pumps, and what pharmacy access, MiniMed’s split from Medtronic, and GLP-1s mean for adoption.
Qualitate’s expert AI Interviewer conducted one-on-one interviews with 51 US physicians in nine days (November 2-10, 2026), including 41 endocrinologists (8 of them pediatric) and 10 primary care physicians. Interviews lasted a median of 40 minutes.
Download the full 40-page report via the sidebar form.
Key takeaways
- Pump use rising: Physicians expect type 1 pump penetration to rise from 68% at the end of 2025 to 84% by the end of 2028, and penetration among type 2 patients on intensive insulin to rise from 28% to 43%.
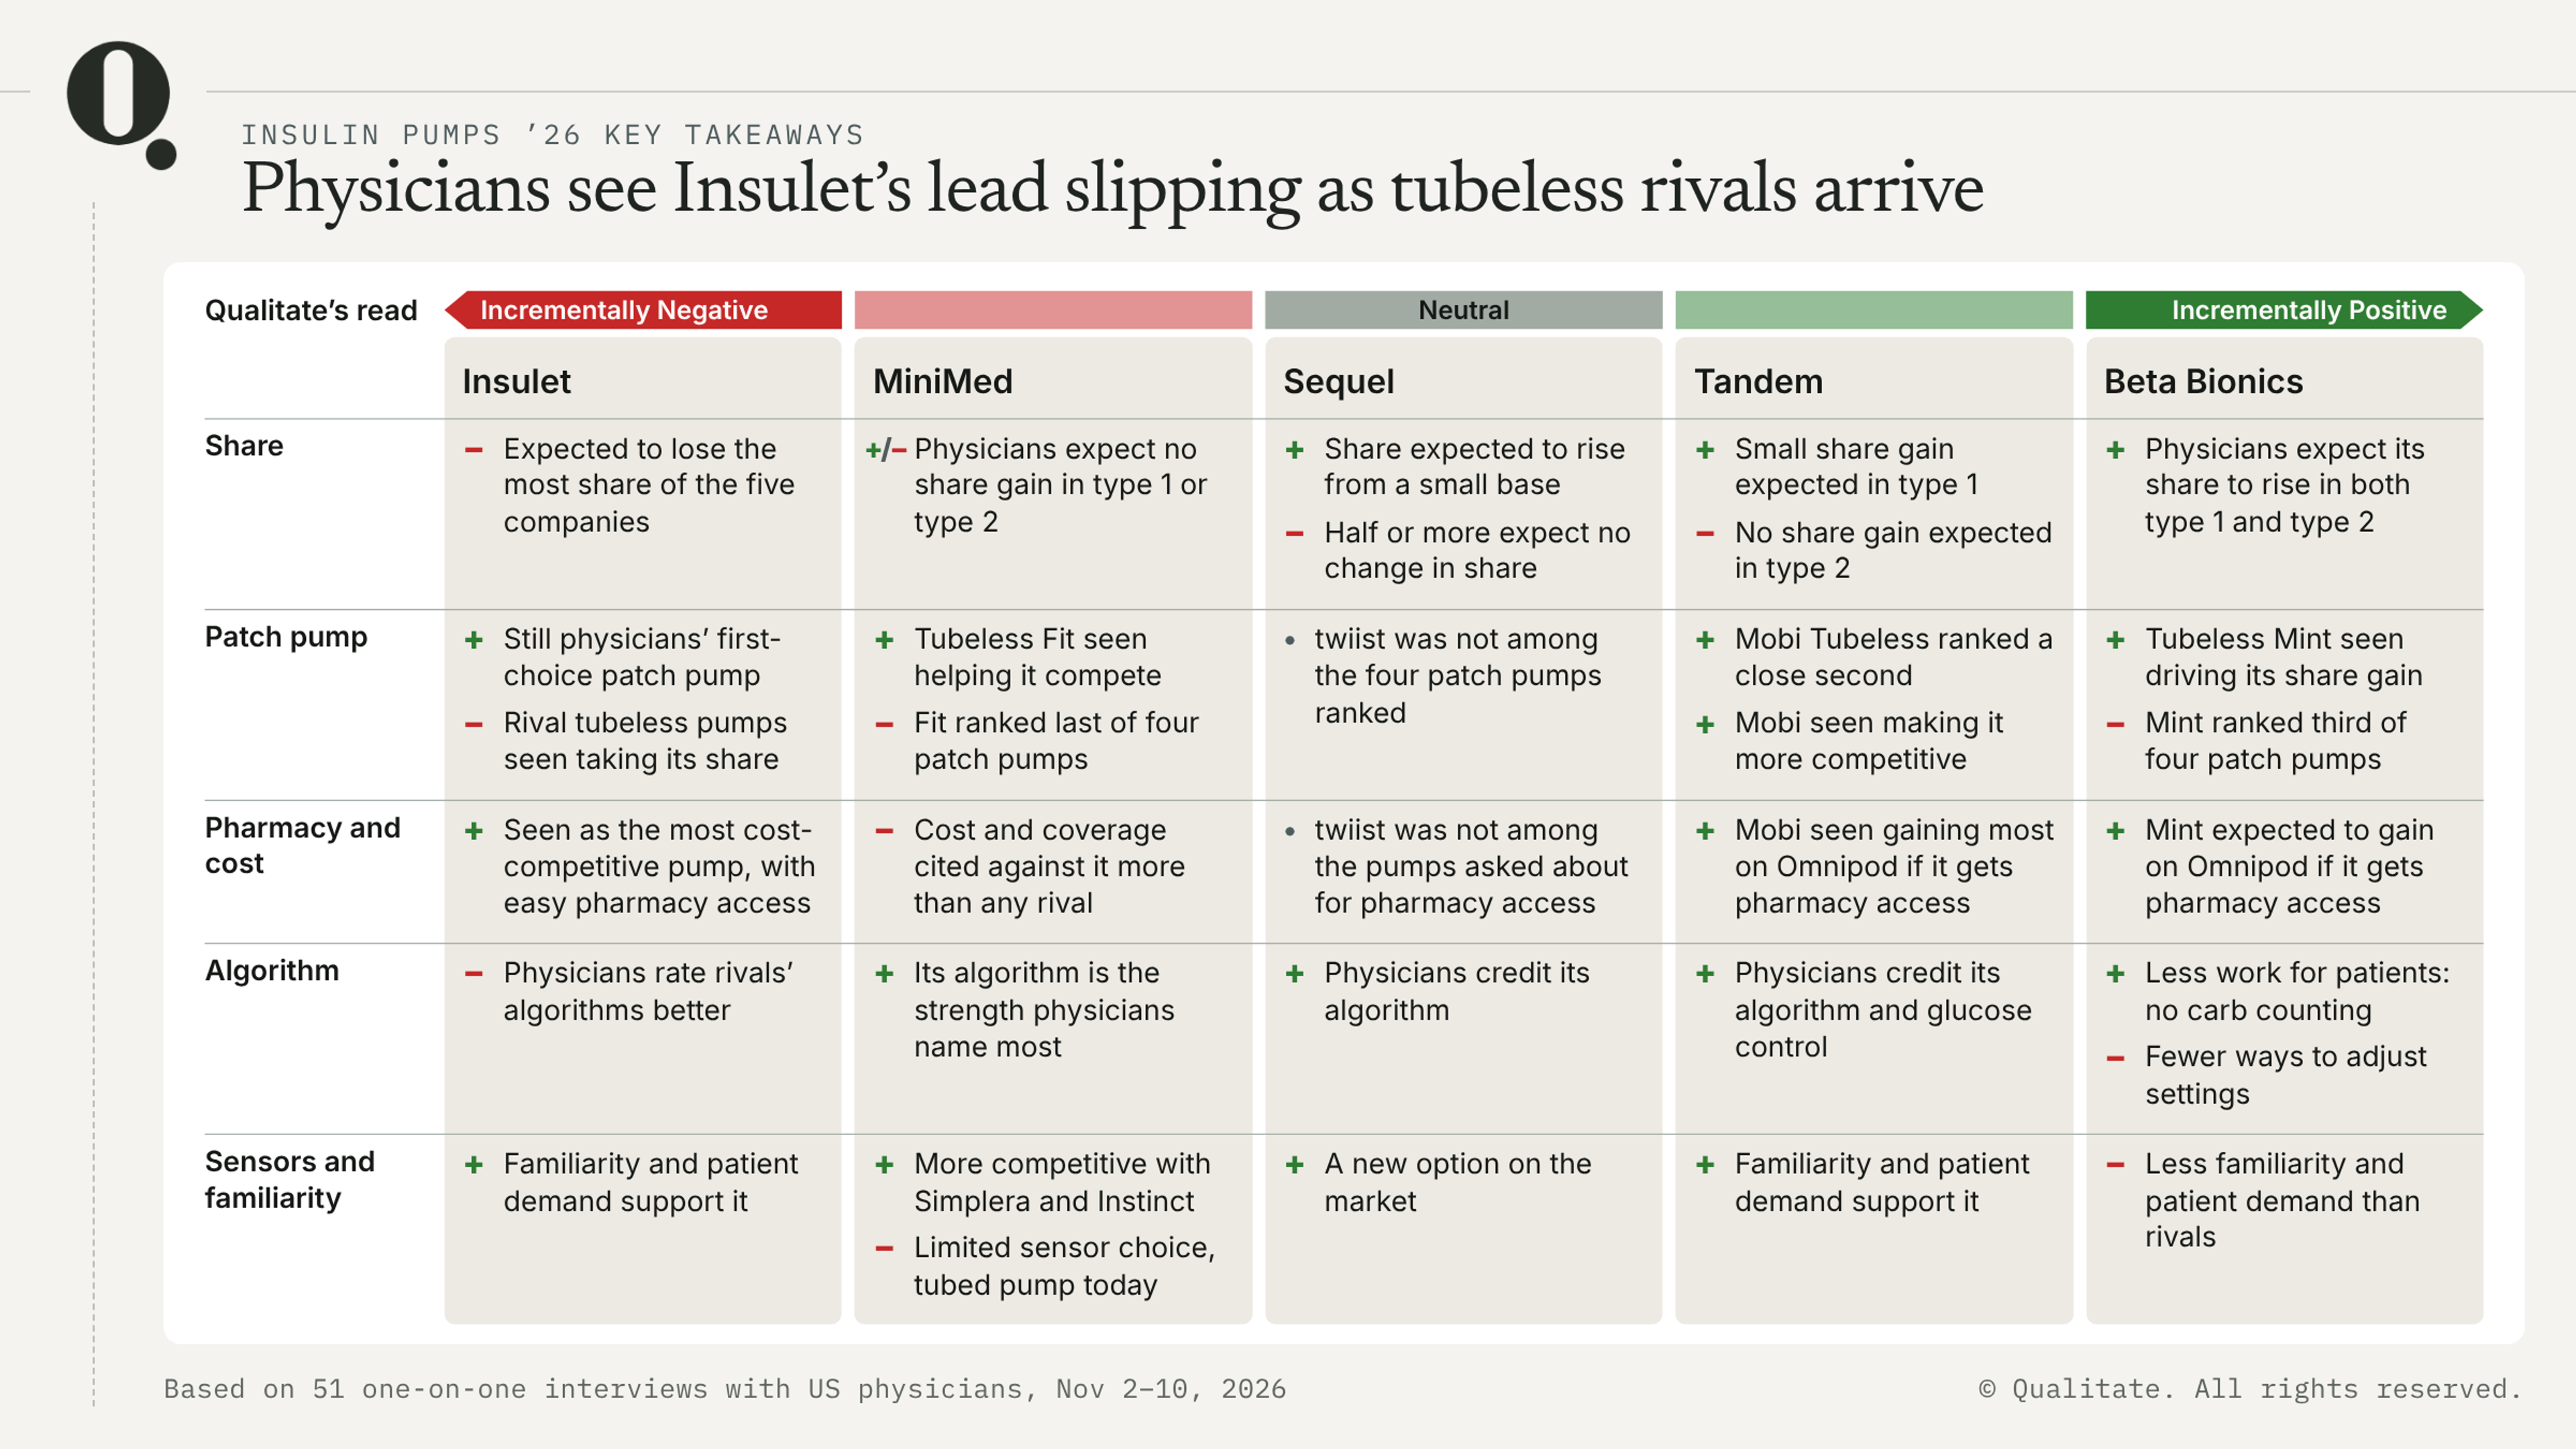
- Omnipod losing share: Physicians expect Omnipod’s share of type 1 pump patients to fall from 47% to 38% by the end of 2028, as rival tubeless pumps launch and pharmacy access expands.
- Beta Bionics the biggest gainer: Beta Bionics is expected to be the biggest share gainer in both type 1 and type 2, driven by its upcoming tubeless Mint and algorithm ease of use.
- Tandem stabilizing: Tandem’s share losses look to be stabilizing, with physicians crediting its upcoming Mobi Tubeless, which they rank a close second to Omnipod 6 among the new patch pumps.
What you get in the full 40-page report
- Pump market penetration through 2028: Type 1 and type 2 on intensive insulin, differences between endocrinologists and primary care physicians, implied pump patient growth, and the drivers and barriers to adoption.
- Manufacturer share: Insulet, Tandem, Beta Bionics, MiniMed and Sequel by patient type through 2028, with the reasons physicians give for each company’s gains and losses.
- New tubeless pumps and pharmacy access: How physicians rank Omnipod 6, Mobi Tubeless, Mint and MiniMed’s Fit and why, and how pharmacy access and up-front cost shape competition.
- MiniMed after its split from Medtronic: The 780G with Simplera and Instinct, its strengths and weaknesses, rep contact since the split, and physicians’ adoption outlook.
- GLP-1s and type 2 pump starts: GLP-1 penetration, its effect on pump starts, expected type 2 starts through 2028, and how many patients stop a pump.
To access the full physician transcripts and learn how you can run your own medtech research projects in days, book a demo.
Are you a physician? Join our expert panel.